“What’s the UK job market like?”
The October 2026 KPMG & REC UK REPORT ON JOBS has been published featuring survey results from mid/late September.
The full report is posted here
Jon Holt, Group Chief Executive and UK Senior Partner KPMG, said:
“For the second month in a row we are seeing the jobs market starting to flicker back to life, with businesses increasing their hiring across both permanent and temporary roles, and for the first time in over two years vacancies grew in the private sector. But this remains a fragile recovery”
Maxine Bligh, REC’s Chief Membership & Innovation Officer, in a possibly overly bullish assessment, said:
“The permanent jobs market is revving its engine, with a second successive month of growth. The last time we saw a sustained run of growth in permanent placements was between March 2021 and September 2022. If this trend continues, we could see genuine momentum building across the labour market, with both permanent and temporary hiring moving in the same direction.”
Key findings are:
- Permanent placements rise for second month in a row
- Permanent pay inflation softens in September with renewed slowdown in perm salary growth
- Vacancy numbers fall at softest rate since August 2024
- Staff availability rises at weakest pace in three years
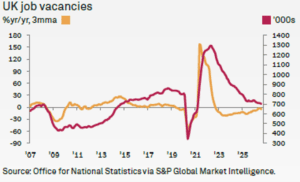
- ONS figures indicate the number of vacancies in the UK continued to decline in the three months to August
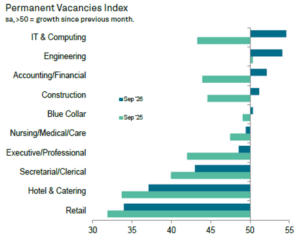
- Higher demand for permanent workers was recorded in half of the ten monitored job sectors during September led by IT & Computing and Engineering
- The sharpest falls in vacancies were signalled across Retail and Hotel & Catering categories
Appointments
Permanent placements rise again in September but temp billings growth slips to five-month low
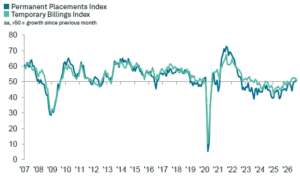
September’s survey indicated that permanent job placements across the UK increased for the second consecutive month. Growth accelerated compared with August, taking the seasonally adjusted index to its highest level in four years, although the overall increase remained modest.
Recruiters reporting an increase in permanent appointments attributed this to greater business activity and company expansion, supported by growing confidence in the economic outlook. However, recruitment freezes and weaker demand for permanent employees in certain sectors continued to constrain growth.
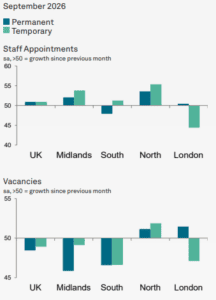
Permanent placements rose in three of the four English regions surveyed, with the North of England recording the strongest growth. The South of England was the only region to report a decline.
Vacancies
Softest fall in vacancies since August 2024
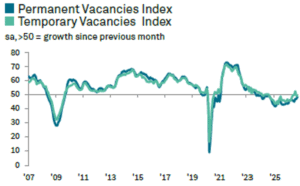
UK recruitment consultancies reported a further decline in demand for staff during September, although the reduction was modest and less pronounced than in previous months. The seasonally adjusted index rose from 47.0 in August to 48.5, indicating the slowest rate of contraction in just over two years. Demand weakened slightly for both permanent and temporary staff.
Permanent & temporary vacancies
Permanent job vacancies continued to decline in September, extending a downturn that has now lasted for more than three years. However, the rate of decline eased to its lowest level since August 2024 and was relatively modest. Temporary vacancies also fell for the second consecutive month, with the pace of reduction remaining mild and broadly unchanged from August.
Public and private sector vacancies
September’s survey revealed an increase in private sector demand for both permanent and temporary staff. Significantly, this was the first rise in permanent vacancies in the private sector for more than two years. In contrast, public sector recruitment remained weak, with substantial declines in demand for both permanent and temporary workers.
Vacancies by Sector
Demand for permanent employees increased in five of the ten sectors surveyed during September, with IT & Computing and Engineering recording the strongest growth. In contrast, Retail and Hotel & Catering experienced the most significant declines in job vacancies.
Temporary vacancies increased in just three sectors during September: Blue Collar, IT & Computing and Nursing/Medical/Care. Demand declined across the remaining seven sectors, although the extent of the downturn varied considerably. Engineering experienced a relatively modest reduction in vacancies, while Retail recorded a particularly sharp fall.
ONS Data
Office for National Statistics data shows the number of UK job vacancies continued to fall in the three months to August, declining by 8,000 compared with the three months to May. This brought the total number of vacancies to 702,000, the lowest level since the three months to April 2021. Excluding the pandemic period, vacancies have not been this low since the three months to October 2014.
Staff availability
Candidate supply increases at softest pace in three years
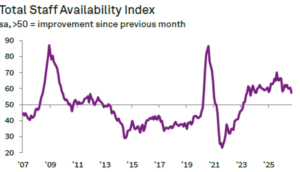
The availability of candidates continued to increase in September, with the seasonally adjusted Total Staff Availability Index falling from 60.6 in August to 57.2. This extended a sustained rise in candidate numbers that has now continued for more than three-and-a-half years. Although the increase remained substantial, it was the smallest recorded since September 2023, largely reflecting a slowdown in the growth of available permanent candidates.
The number of candidates available for permanent positions continued to rise in September, marking 43 consecutive months of growth. Although the increase remained significant, it was the slowest recorded in three years. Recruiters frequently cited redundancies and a shortage of job opportunities as the main reasons behind the growing number of jobseekers.
Permanent candidate availability increased across all four English regions surveyed, although there were considerable regional differences. The North of England experienced the strongest growth, while London recorded only a marginal increase.
Pay pressures
Permanent salary growth slows again in September
Starting salaries for permanent employees continued to rise in September, extending a period of sustained pay growth to more than five-and-a-half years. However, the rate of increase slowed for the first time in four months and, although still relatively strong, remained below its long-term average.
Recruiters reported that competition for high-calibre candidates continued to drive salaries upwards, although employers’ efforts to contain costs and the growing availability of candidates helped moderate increases. Regionally, the North of England recorded particularly strong salary growth, while increases elsewhere in England were more modest
ONS Data
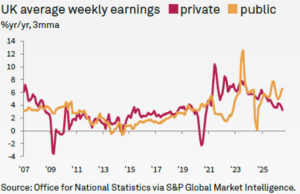
Latest data from the Office for National Statistics (ONS), is as usual a bit out of date. Employee earnings continued to increase year-on-year in the three months to July, although annual pay growth slowed to 3.9%. This matched the rate recorded in February 2026 and was the lowest since November 2020.
The slowdown was largely attributable to weaker private sector pay growth, which fell to 3.2%, its lowest level since the three months to October 2020. In contrast, public sector earnings rose by 6.6%, the strongest increase recorded so far this year. The Office for National Statistics attributed this partly to NHS pay increases being implemented earlier in 2026 than in 2025.
London job market
KPMG and REC also produce a London job market analysis.
Anna Purchas, London Office Senior Partner at KPMG UK, said:
“September’s figures point to a London jobs market that is resilient. London was one of only two English regions where demand for permanent staff increased in September. That tells us that talent remains in demand in the capital, even as businesses are being careful about taking on additional costs.“
Maxine Bligh, Interim Chief Executive at the Recruitment and Employment Confederation (REC), said:
“With permanent placements rising for a third consecutive month, as a key piston in the engine of the UK economy, London’s recovery is an encouraging sign. Permanent vacancies also keep rising in London. The downturn in temp billings last month is a surprise, but it must be seen in the context of the previous four months of growth.”
Marginal rise in permanent placements
Recruiters in London reported a further increase in permanent job placements in September, supported by stronger business activity that encouraged employers to recruit additional staff. However, the rate of growth slowed again and was considerably weaker than at the beginning of the quarter, when the current period of expansion began.
Permanent placements also increased across the UK as a whole, with growth outpacing that recorded in London.
Job vacancies
Demand for permanent staff in London continued to strengthen in September, with vacancies increasing for the sixth consecutive month. Although growth remained modest, it was slightly stronger than in August.
In contrast, temporary recruitment weakened following four successive months of rising demand. The decline in temporary vacancies was substantial and represented the sharpest contraction since March.
Upturn in permanent staff supply eases notably
The availability of candidates for permanent roles in London increased again in September, extending a period of continuous growth to 46 months. Recruiters frequently identified redundancies as a major factor contributing to the rising number of jobseekers.
However, the rate of increase slowed considerably, making September the second-weakest month for growth during this period, marginally ahead of March 2023. London also recorded the smallest increase in permanent candidate availability among the four English regions surveyed.
Starting salary inflation weakest in six months
Starting salaries for permanent employees in London continued to increase in September, although growth was modest. Recruiters attributed the rise to competition for suitably qualified candidates and ongoing cost of living pressures. However, salary growth slowed further to its weakest rate since March, remaining below both the long-term average and the UK average.
Regional comparison
Staff appointments
Permanent job placements across the UK increased for the second consecutive month in September, following August’s first rise in almost four years. Although growth remained marginal, it was the strongest recorded since September 2022. Three of the four English regions surveyed reported an increase, with the North of England joining London and the Midlands in recording growth. The North experienced the strongest expansion, while the South of England saw a further modest decline.
Temporary staff billings also rose nationally in September, although growth was marginal and the weakest since the current period of expansion began in April. All regions except London reported an increase, with the capital experiencing its first fall in five months. The North of England recorded the strongest growth, despite a slowdown compared with August.
Candidate availability
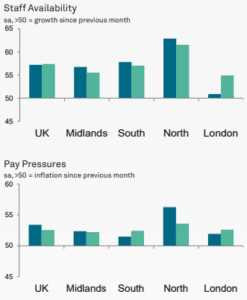
The number of candidates seeking permanent employment continued to rise sharply across the UK in September, although the rate of increase slowed to its lowest level in three years. Growth moderated in three of the four English regions, with the Midlands the only exception. The North of England recorded the largest increase in candidate availability, while London experienced the smallest.
The supply of temporary workers also increased significantly across the UK, with growth accelerating to a three-month high. Three of the four regions saw a faster rise in candidate numbers, led by the North of England. London was the only region where growth slowed and also recorded the smallest increase.
Pay pressures
Starting salaries for permanent employees continued to increase across the UK in September, although the rate of growth eased compared with August and remained below historical norms. Salary inflation accelerated in the North of England and the Midlands, which recorded the strongest and second-strongest increases respectively. Growth slowed in London and the South of England, with the latter experiencing the smallest rise.
Hourly pay rates for temporary workers also continued to increase nationally, although wage inflation slowed to its lowest level in four months. All four English regions reported weaker growth than in August. The North of England recorded the largest increase in temporary pay, while the Midlands experienced the most modest rise.
The Prism Executive Recruitment perspective: management consultancy recruitment
The Decline in the Management Consulting Job Market
The management consulting recruitment market has faced sustained difficulties since the latter part of 2022. From mid-2023, the Big Four and other leading consulting firms began announcing successive rounds of redundancies. This included strategy consultancies, which have traditionally proved more resilient during weaker markets. Meanwhile, many smaller consulting businesses have reduced their permanent workforces and scaled back their use of associates, often with considerably less publicity.
This has created a significant mismatch between the supply of experienced management consultants looking for new roles and the number of vacancies available. With relatively few opportunities in the market, consulting employers have been unable to accommodate the increasing number of unemployed consultants seeking their next position.
A succession of prominent announcements during 2024 and 2025 illustrated the difficult conditions facing the sector. In May 2024, reports emerged that “PwC asks for silence from departing staff in programme of UK job cuts,” as the firm undertook another substantial voluntary redundancy programme.
Further concerns emerged the following month, when it was reported that “Consultants to lose £3bn of UK government work under plan to halve advisory spend.”
In July 2024, the Financial Times reported that “UK consultant numbers shrink as companies cut back on external advice. Headcount fell 3% last year with firms axing jobs and moving staff as post-pandemic boom fades.”
Further redundancy announcements followed during the latter part of the year. October brought reports that “Deloitte axes 250 UK employees in performance-related cull.” Two months later, this was followed by the announcement that “Deloitte accelerates UK layoffs with fresh redundancy round.”
EY also outlined potential workforce reductions in December 2024, commenting that “Regrettably, proposals put forward in part of the UK consulting practice may result in a reduction of 150 roles”.
Challenging news continued during 2025. Notable September headlines included “PwC UK cuts jobs as revenue growth slows sharply” and “Deloitte UK’s revenues fall for first time in 15 years”. Earlier, in June, weakening client demand had been highlighted when “Accenture says CEOs are postponing hiring consultants due to uncertainty”.
There have, however, been some more positive indications during 2026, with headlines including:
“Consultancies set for fastest growth in years on back of AI boom”
“Consultants cash in on Europe’s defence pivot”
And, suggesting that AI may not result in a “jobs apocalypse” in the sector “Human skills ‘matter even more’ for early consultancy career roles”
Potential Reasons for the Downturn:
- Overly optimistic hiring and pay rises in 2022: consulting firms recruited heavily during 2022 and offered substantial salary increases, adding significantly to their cost bases. These decisions were based on expectations of continued growth that ultimately failed to materialise.
- Economic slowdown since: management consulting is particularly sensitive to changes in the wider economy. Even relatively modest economic weakness can cause employers to pause recruitment, with redundancies potentially following if demand remains subdued.
- Cautious re expansion: many consulting firms continue to trade reasonably well, but persistent uncertainty has discouraged them from making significant additions to permanent headcount.
- Sector growth subdued: a January 2026 survey of UK consulting leaders forecast sector growth of 5.7% for 2026, representing the weakest projected growth rate since 2020.
Other indicators
In related news a mixed picture again:
- The NatWest Business Growth Tracker from July says “UK businesses continued to project output growth over the coming 12 months, with confidence levels across both SMEs and mid-market firms improving from May. While optimism remained below long-run averages, easing cost pressures helped support a more positive outlook.”
- The S&P UK Services Purchasing Managers’ Index (PMI) from October 2026 states: “September data pointed to a further upturn in UK service sector output, which confirmed a sustained rebound in business conditions during the third quarter of 2026. However, new order intakes increased only marginally and job cuts persisted.”
- The S&P Global UK Manufacturing PMI rose to 51.9 in September 2026, up from 51.7 in August and broadly in line with the preliminary estimate and market expectations. The reading signalled an expansion in manufacturing activity for the 11th consecutive month, although the pace of growth eased slightly toward the end of the third quarter.
- The Lloyds Bank Business Barometer from September 2026 has as key highlights:
- UK business confidence falls 12 points to 41%, a 17-month low
- Economic optimism leads the decline amid heightened global uncertainty
- Trading prospects weaken as firms become more cautious about activity
- Hiring expectations ease as cost management becomes a greater priority
- Confidence falls across most regions and sectors, although retail improves
- The IoD Directors’ Economic Confidence Index, from 1 October which measures business leader optimism over prospects for the UK economy, fell to -54 in September, from -49 in August 2026. They said “September’s results show a growing divide between confidence in businesses’ own prospects and confidence in the wider economy. Business leaders are more confident about their own organisations, and revenue expectations have strengthened. But cost pressures remain high, squeezing margins and leaving some firms having to ‘run to stand still’. Investment and hiring intentions unsurprisingly therefore remain subdued.”
- While the CIPD’s Summer 2026 Labour Market Outlook released in August states “Our latest Labour Market Outlook finds that UK employer confidence remains close to record lows, outside of the pandemic, and has shown no signs of recovery since spring 2025. Of the 2000+ employers surveyed, only 62% of employers plan to recruit over the next three months, with most focusing on maintaining staff levels.”
- The Page Group, very much an economic bellwether in professional and executive hiring, issued a trading update in October 2026 stating “The Group delivered its first quarter of growth since Q4 2022. We saw growth continue in Asia Pacific, the Americas and Southern Europe, with trading continuing to be more challenging, albeit stable, across France, Northern Europe and the UK. In total, c. 50% of the Group was in growth in Q3.”
- BDO’s Business and Employment Indexes states “Business growth slows” and BDO’s Employment Index, a combination of hiring intentions, headcount and labour demand “remained unchanged at 93.10, holding just above its 15-year low and below the 95-point threshold for the 21st consecutive month. High energy and business costs are likely to keep discouraging hiring, while uncertainty ahead of the approaching Autumn Budget adds a further brake on recruitment decisions.”
- The comprehensive Adzuna UK Job Market Report stated “UK job vacancies rose for a fourth consecutive month in May, climbing +2.85% to 799,737. The sustained run of growth – the first since the downturn began in mid-2025 – has narrowed the annual decline from -16.1% in January to just -6.84% in May, the smallest gap recorded since vacancies began falling.”
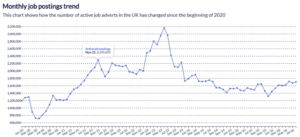
- The REC’s Labour Market Tracker, which reviews job postings, updated in September 2026, shows a level broadly unchanged since August 2024 albeit with encouraging signs in 2026
- The most recent quarterly ManpowerGroup Employment Outlook Survey , released in September 2026 surveying 39,000 employers across 42 countries on the state of the labour market globally for Q4 2026, puts the UK below average with regard to hiring expectations.
Methodology
The KPMG and REC UK Report on Jobs is compiled by S&P Global from responses to questionnaires sent to a panel of around 400 UK recruitment and employment consultancies.
For more information on the job market, or to discuss your hiring or career plans please contact Chris Sale, Managing Director, Prism Executive Recruitment via [email protected]